Why Proper Recordkeeping Matters When Your Business Insurance Is Audited
For many business owners, the word “audit” can create a sense of anxiety. However, an insurance premium audit is a normal part of owning a business and having certain types of commercial insurance. The purpose of an audit is generally to compare the information used to estimate your premium at the beginning of the policy period with your company’s actual operations during that period. Depending on the results, your final premium could increase—or, in some cases, decrease.
One of the best ways to make the process easier is to keep accurate, organized records throughout the year.
What Is an Insurance Premium Audit?
When a commercial insurance policy is written, the insurance company often has to estimate certain factors because the actual figures for the upcoming policy period are not yet known. Those estimates might include payroll, sales, employee classifications, subcontractor costs, or other measures of your business activity.
At the end of the policy period, the insurance company may conduct an audit to determine what actually occurred. The auditor may compare payroll reports, financial records, tax documents, sales information, and other records to the figures originally used to calculate your premium.
The audit is not necessarily an indication that something is wrong with your business. It is primarily a way of making sure the premium accurately reflects your actual business exposure.
Which Commercial Insurance Policies Are Commonly Audited?
Several types of commercial insurance can be subject to premium audits. Common examples include:
- Workers’ Compensation – Typically based largely on payroll and employee job classifications.
- General Liability – Depending on the business, premiums may be based on payroll, sales, or other factors.
- Commercial Auto/Garage Liability – Certain commercial auto or garage-related policies may require information about employees, operations, vehicles, or other exposures.
- Other payroll-based or sales-based commercial policies – Some policies use payroll, gross sales, receipts, or other business measurements to determine the premium.
The exact audit requirements depend on the insurance company, policy, state, type of business, and how the policy premium was calculated.
What Records Should Your Business Keep?
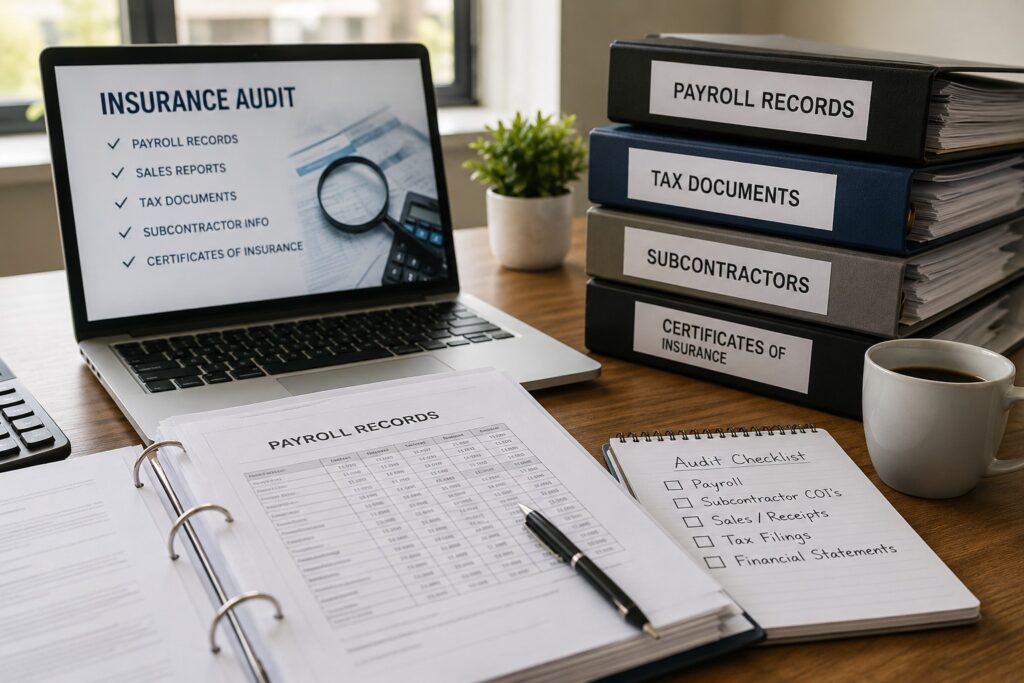
Good recordkeeping throughout the policy year can make a significant difference when an auditor requests documentation. Businesses should consider maintaining organized records such as:
Payroll Records
- Employee names
- Gross wages
- Overtime and double-time wages
- Job duties and classifications
- Dates of employment
- State where employees work
- Separate records for certain types of compensation when applicable
Tax Records
- Federal payroll tax filings, such as Form 941
- State unemployment wage reports
- Federal and state income tax returns
- 1099 forms
- Other applicable tax filings
Sales and Financial Records
- Sales journals
- General ledgers
- Profit and loss statements
- Income statements
- Cash receipts
- Check registers
- Cash disbursement records
Subcontractor Records
- Subcontractor names
- Contracts
- Invoices
- Description of work performed
- Amounts paid
- Dates the work was performed
- Labor and material costs
- Certificates of Insurance (COIs)
Keeping valid Certificates of Insurance for subcontractors is particularly important. Depending on the circumstances and applicable rules, an uninsured subcontractor’s payroll or labor costs may affect the premium calculation. Documentation showing that a subcontractor carried appropriate Workers’ Compensation and General Liability coverage can therefore be extremely important during an audit.
Don’t Wait Until the Audit Is Scheduled
One of the biggest mistakes a business owner can make is waiting until an auditor contacts them before organizing their records.
Instead, maintain an insurance audit folder throughout the year, either electronically or in paper form. Save payroll reports, tax filings, subcontractor documentation, certificates of insurance, sales records, and other relevant information as you go.
It is also important to keep records that accurately correspond to the policy period. Insurance companies may use multiple sources of information to verify the figures provided during an audit. For example, payroll records may be compared with tax filings and other financial documentation.
Accurate Records Can Help Prevent Surprises
An audit can result in an additional premium if your company’s actual payroll, sales, or other exposures were higher than originally estimated. Conversely, if your actual exposure was lower, the audit may result in a lower final premium or potentially a return of premium, depending on the policy and circumstances.
Accurate records also give your insurance agent and carrier a clearer picture of how your business operates. If your company experiences significant changes in payroll, staffing, sales, operations, or subcontractor usage during the year, it may be worth discussing those changes with your insurance professional rather than waiting until the audit.
Make Recordkeeping Part of Your Business Routine
Insurance audits don’t have to be stressful. The key is preparation. By keeping accurate records throughout the year and maintaining documentation related to payroll, sales, subcontractors, tax filings, and business operations, you can make the audit process considerably easier and reduce the likelihood of unnecessary confusion or surprises.
If you have questions about your commercial insurance, premium audits, or whether your current coverage is keeping pace with changes in your business, Morning Star Agency Insurance Services, Inc. is here to help. Contact Morning Star Insurance for your commercial and personal insurance needs. Our experienced team can help you review your coverage and make sure your insurance program continues to fit your business as it grows and changes.